Jaspreet Dhugga – Mortgage Broker Brampton, GTA And Ontario
Down Payment for a House in Brampton: How Much Do You Need
- Home
- Down Payment for a House in Brampton: How Much Do You Need
A Brampton home can’t be bought with zero down under Canada’s minimum down-payment rules.
It’s understandable to focus on the down payment first. It’s a major part of the cash you’ll need, but the minimum depends on the home’s purchase price, and closing comes with other costs. This guide explains how much down payment a house in Brampton requires at different prices, what a larger down payment can change, and which programs may help eligible buyers build their funds. You’ll also learn how to plan your next steps, whether you’re preparing to buy soon or still saving for a deposit.
Key Takeaways
- Work out the minimum from the purchase price, not a single flat percentage. The calculation changes across price thresholds.
- A down payment below 20% will typically mean mortgage loan insurance, so factor that into your affordability planning.
- If you’re an eligible first-time homebuyer, the Home Buyers’ Plan lets you withdraw up to C$60,000 per person from an RRSP, according to the Canada Revenue Agency.
Minimum down payment calculation for a $950,000 home
The minimum down payment changes with the purchase price, so one percentage won’t fit every Brampton home.
Calculating the Minimum by Purchase Price
For a purchase priced at C$950,000, apply the minimum rate to each portion of the home price, not the full amount at one rate. This estimate helps you understand the deposit required before planning your financing and seeking mortgage approval.
Minimum Down Payment by Price Range
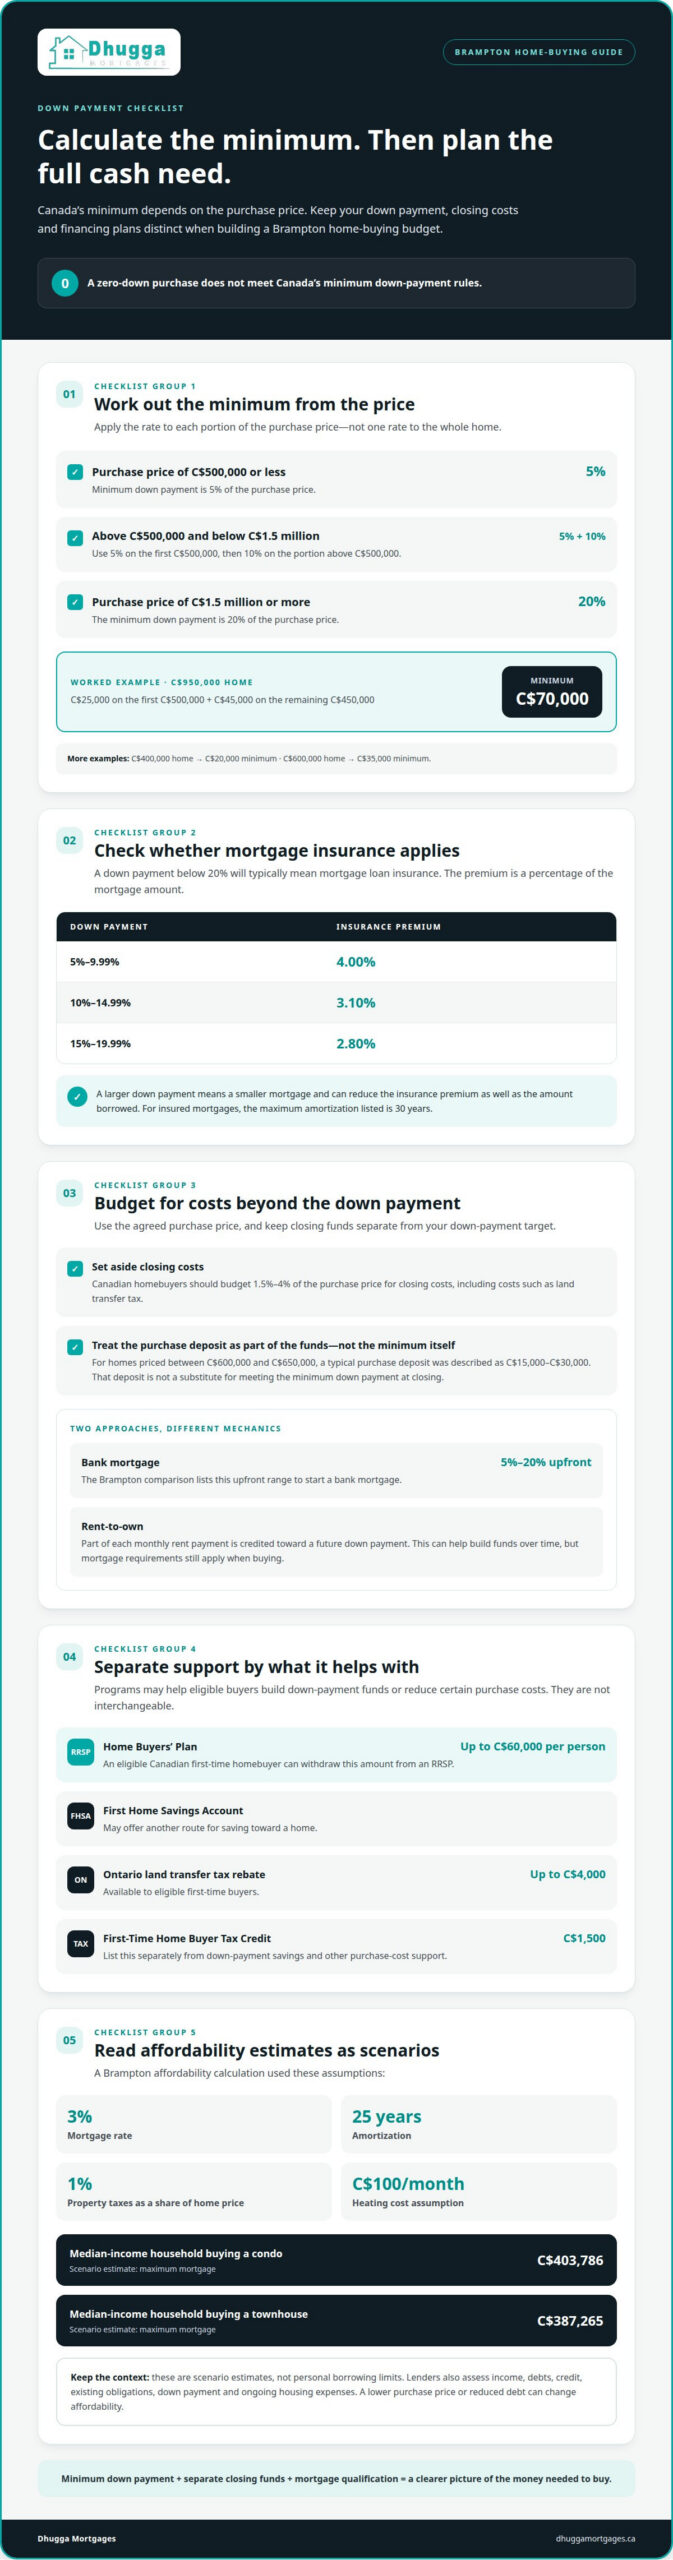
Canada’s minimums vary by purchase-price range. For a Canadian home purchase priced at C$500,000 or less, the minimum down payment is 5% of the purchase price, according to Canada Mortgage and Housing Corporation. For a purchase above C$500,000 and below C$1.5 million, Canada Mortgage and Housing Corporation sets the minimum at 5% of the first C$500,000 plus 10% of the portion above C$500,000. The required down payment can depend on the home’s price and the buyer’s circumstances.
Canadian Minimum Down Payment Rules by Price
The minimum applies to the actual purchase price, not a citywide average or a general estimate. Set aside closing funds separately: Canadian homebuyers should budget 1.5% to 4% of the purchase price, including costs such as land transfer tax. A broker can help model the down payment alongside financing needs.
Use the agreed purchase price to calculate your target, and keep the down payment separate from closing costs. This gives you a clearer picture of the funds you’ll need to complete the purchase.
What down payment is required for a mortgage in Canada?
In Brampton, putting down less than 20% can reduce the cash needed upfront, but mortgage loan insurance typically applies. The trade-off is a smaller initial hurdle and a larger mortgage, plus the insurance premium.
Mortgage Default Insurance and Premiums
Mortgage default insurance protects the lender if a borrower can’t repay, and its premium affects your total borrowing cost. Canadian homebuyers who put down less than 20% of the purchase price will typically need mortgage loan insurance, according to Canada Mortgage and Housing Corporation. For an insured Canadian mortgage with a down payment of 5% to 9.99%, the mortgage default insurance premium is 4.00% of the mortgage amount, according to Canada Mortgage and Housing Corporation. At 10% to 14.99% down, the premium is 3.10%; at 15% to 19.99%, it is 2.80%. A larger down payment can therefore reduce the premium as well as the amount borrowed.
How Down Payment Size Affects Mortgage Costs
A larger down payment means a smaller mortgage principal, which can reduce interest paid and build home equity sooner. A smaller deposit preserves more savings for other needs, but increases the mortgage and may add insurance costs. Buyers still need to qualify for the mortgage based on their financial circumstances. For insured mortgages, the maximum amortization listed is 30 years, which affects the time available to repay.
At C$1.5 million or more, the minimum down payment is 20% of the purchase price, according to Canada Mortgage and Housing Corporation. Rent-to-own is different from a bank mortgage: the Brampton comparison lists 5-20% upfront to start a bank mortgage, while rent-to-own credits part of each monthly rent payment toward a future down payment. That can help build funds over time, but it doesn’t remove the need to meet mortgage requirements when buying. To discuss how your deposit affects mortgage costs, review your mortgage options.
Can I buy a home without a down payment?
No. A zero-down purchase doesn’t meet Canada’s minimum down-payment rules. The amount you need depends on the purchase price, so use the minimum as a starting point and account for closing costs and your wider budget. Your income, credit, savings and mortgage amount also affect affordability.
For example, a C$400,000 home has a C$20,000 minimum down payment. At C$600,000, the minimum is C$35,000. These examples show why a calculator should use the actual price and deposit, rather than a single percentage.
Condo prices can change the savings target. Treat each figure as an example based on its stated price, not a fixed amount for every condo purchase.
That timeline reflects the study’s assumptions, including saving 20% of total median income each year. Your income and existing savings change the calculation.
A separate estimate put Brampton’s median home price at C$820,000 for 2026. For homes priced between C$600,000 and C$650,000, a typical purchase deposit was described as C$15,000-C$30,000. That initial deposit is part of the purchase funds, not a substitute for meeting the minimum down payment at closing. Build a budget around both amounts, then use a mortgage calculator to test how different savings levels affect your financing needs.
Home-buying programs and incentives
Several Canadian programs can help eligible buyers build down-payment funds or reduce certain purchase costs. They don’t replace mortgage qualification: a lender still assesses income, debts, credit and the home’s ongoing expenses.
Under the Home Buyers’ Plan, an eligible Canadian first-time homebuyer can withdraw up to C$60,000 per person from an RRSP, according to the Canada Revenue Agency. A First Home Savings Account may offer another route for saving toward a home. Ontario’s land transfer tax rebate can save eligible first-time buyers up to C$4,000, while the listed First-Time Home Buyer Tax Credit is C$1,500. These supports affect different parts of buying, so include them separately in your budget rather than treating them as interchangeable cash.
A home affordability calculator helps estimate a manageable purchase price by combining income, monthly housing costs and financing assumptions. One Brampton affordability calculation used a 3% mortgage rate, a 25-year amortization, property taxes equal to 1% of the home price, and C$100 monthly for heating. It estimated maximum mortgages of C$403,786 for a median-income household buying a condo and C$387,265 for a townhouse. These are scenario estimates, not personal borrowing limits. Your monthly debt obligations and down payment also affect what a lender may approve.
A mortgage stress test can affect how much a Brampton buyer may be able to borrow. Lenders also weigh documented income and existing obligations, because those determine whether monthly payments fit the household budget. A lower purchase price or reduced debt can change the affordability calculation.
Before buying, map each program to its purpose: RRSP or FHSA funds toward savings, the Ontario rebate toward land transfer tax, and the tax credit as a separate incentive. Keep closing costs and the mortgage obligation in your total plan. Discuss your home-buying mortgage options and how your funds may fit the purchase.
Dhugga Mortgages
Dhugga Mortgages can help Brampton buyers turn down-payment rules into a mortgage plan that reflects their purchase and finances. First-time buyers can explore First-Time Home Buyer Mortgages and consider how savings, income, credit and target home price fit together. Self-employed buyers can explore Self-Employed Mortgages, where income documentation is part of the financing picture.
Bring your expected price range, down-payment funds and questions about mortgage insurance or affordability. Reviewing these details can clarify the mortgage amount you may need and how financing options relate to your purchase. It’s a practical step before committing to a home, especially if you’re weighing a minimum deposit against a larger down payment.
Contact Dhugga Mortgages to discuss your Brampton home purchase.
Plan your next move with confidence
Your next step is to connect your down-payment target with a mortgage plan that fits your income, savings and other financial commitments. Knowing how much down payment a house in Brampton requires is only part of the decision. Your overall budget should also allow for ongoing home costs and a financial cushion after closing.
Dhugga Mortgages offers First-Time Home Buyer Mortgages for buyers preparing to purchase. Existing homeowners can also explore Mortgage Refinancing or Debt Consolidation when reviewing their wider finances. Start with your plans, the funds you expect to use and any questions you still need answered.
Bring those details together before making your next move. Contact Dhugga Mortgages to discuss your options and take a clear next step toward your Brampton home purchase.
Frequently Asked Questions
Can closing costs be part of the down payment?
No. Closing costs are separate funds needed to complete the purchase, so include them in your cash plan alongside the down payment. Canadian homebuyers should budget 1.5% to 4% of the purchase price for closing costs. These can include legal fees, registration costs and land transfer tax. Keeping the two amounts separate helps prevent a shortfall when the transaction closes.
Can you borrow your down payment for a house in Canada?
Borrowing may be possible, but an additional loan creates a repayment obligation that affects overall affordability. A lender considers your income, existing debts and expected housing costs when assessing a mortgage application. For example, a personal loan used for the deposit could increase your monthly debt payments and reduce the amount you qualify to borrow. Include both the borrowed funds and repayments in your financing plan.
How much do I need to buy a home in Brampton?
The required amount depends on the purchase price, down payment and closing costs. Your mortgage approval also depends on affordability. Once you know your target budget, connecting with a local brokerage like Pinnacle Realty can help you explore available residential properties throughout Brampton that match your financial criteria.
Is a higher down payment always better?
No. A larger down payment reduces the mortgage balance and may lower interest costs, but using all your savings can leave less flexibility for repairs, moving expenses or income changes. Compare the benefit of borrowing less with the value of keeping accessible cash in reserve. The right balance depends on your monthly budget, other debts and the funds you’ll need after closing.
What does your down payment affect?
Your down payment affects how much you need to borrow, your starting equity and whether mortgage loan insurance typically applies. It can also influence your mortgage payment and the total interest paid over the repayment period. For example, keeping the purchase price constant while increasing the deposit reduces the principal you finance. Consider the down payment alongside ongoing expenses, not as an isolated target.
What is the minimum down payment required to buy a house in Brampton, Ontario?
To work out how much down payment you need for a house in Brampton, apply the purchase-price rules. A Canadian home priced at C$500,000 or less requires a 5% minimum, according to Canada Mortgage and Housing Corporation. Above C$500,000 and below C$1.5 million, the minimum combines 5% on the first C$500,000 and 10% on the amount above it. At C$1.5 million or more, the minimum is 20%.